October sales slowed to 1,592 units, contributing to a year-to-date decline of nearly 11 per cent. While sales have slowed this year, much of the decline was driven by steep pullbacks in resale apartment condominiums and row-style units. Although sales have fallen across all property types, we have seen a pickup in sales of homes that are priced above $1.5 million, which account for less than four per cent of all sales activity.
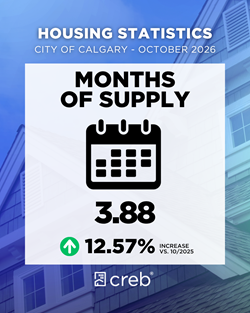
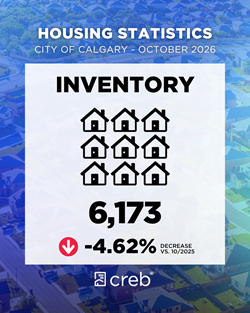
The overall pullback in sales was met with further declines in new listings, causing inventories to trend down in October. In line with typical seasonal behaviour, inventories slowed from September, leaving inventories nearly five per cent lower than October 2025 levels. With 6,173 units in inventory and 1,592 sales, the months of supply remained just below four months. The elevated months of supply is mostly due to shifts in the higher-density apartment and row sectors of the market, which both tend to favour the buyer. Meanwhile, detached and semi-detached markets remain relatively balanced.
“Supply choice in the new, rental and resale markets has taken much of the pressure off prices this year. However, supply choice can vary significantly within the market, resulting in divergent impacts on prices,” said Ann-Marie Lurie, Chief Economist at the Calgary Real Estate Board (CREB®). “Much of the downward pressure on prices is occurring in the oversupplied higher-density segments of the market, while detached and semi-detached prices have remained more stable. Even within the detached market, we see variation as the City Centre and West districts continue to report price gains over 2025, while prices have declined by more than six per cent in the North East district.”
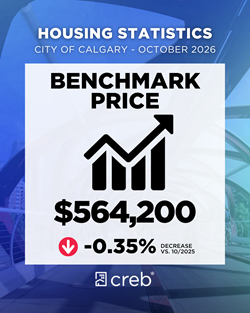
In line with seasonal expectations, October’s benchmark price eased compared with September, and remained similar to last year’s levels. While much of the price adjustment in the market occurred in the second half of 2025, we did not see the same seasonal lift in prices in spring 2026, leaving year-to-date prices nearly three per cent lower than October 2025. Year-to-date benchmark prices ranged from stable in the semi-detached sector to a decline of nearly nine per cent in the apartment condominium sector.
To read the full stats release on October’s housing market for Calgary and surrounding areas, click here.
Find sharable monthly stats from CREB® on Facebook, Instagram and LinkedIn.
Click here to view the full City of Calgary monthly stats package.
Click here to view the full Calgary region monthly stats package.
{ 0 comments…}